The December 15 extension with a potentially defective Form 4868
Hello and welcome once again to The Friday Edition. Phil Hodgen here.
Let’s talk about the December 15 filing deadline and how to get it for nonresident aliens—and a “belt and suspenders” method I use when Form 4868 has a defect (box 9 isn’t checked when it should have been).
I am going to explain this by reference to the 2025 tax year and how you can get an extension until December 15, 2026 to file a timely tax return for a nonresident alien who does not have U.S. wage income subject to withholding.
Two Clarifications
- This does not change the due date for payments. It only extends the deadline for filing Form 1040-NR. See Reg. Section 1.6081-4(c).
- I assume that the individual’s tax year is the calendar year.
The Default Filing Deadline
The normal filing deadlines for an individual’s 2025 Form 1040-NR will either be April 15, 2026 or June 15, 2026. See IRC Section 6072(c) and Reg. Section 1.6072-1(c).
- April 15, 2026 – nonresident aliens with wage income subject to Chapter 24 withholding.
- June 15, 2026 – nonresident aliens with NO wage income subject to Chapter 24 withholding.
Automatic Extension to December 15, 2026
By filing Form 4868 before the applicable default deadline (June 15, 2026), the taxpayer receives an automatic six-month extension. See Reg. Section 1.6081-4(a).
Nonresident aliens without wage income subject to chapter 24 withholding therefore have an automatic extension of six months from June 15, 2026 to December 15, 2026.
Defective Form 4868?
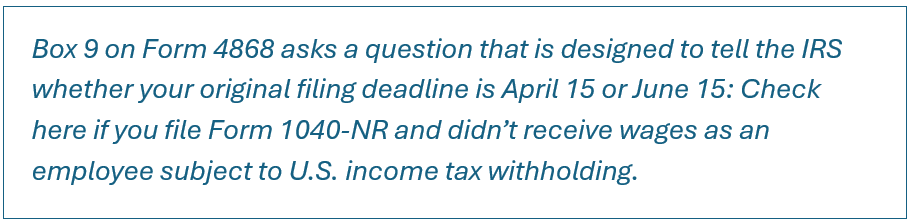
If you check that box, the IRS knows that your original filing deadline is June 15, and they can decide whether you filed a timely Form 4868 (or not!).
I can think of at least three reasons why someone who SHOULD check that box might not check the box.
- Sometimes you don’t know whether the taxpayer will be filing Form 1040 as a resident alien or will be filing Form 1040-NR as a nonresident alien. E.g., you are undecided about whether to take a treaty tie-breaker position to claim treaty nonresident status for the taxpayer.
- Or perhaps you are unsure whether the closer connection exception would allow the taxpayer to claim nonresident alien status.
- Or perhaps you screwed up.
Example
You file Form 4868 on April 1, 2026, well before either the April 15, 2026 or June 15, 2026 filing deadlines.
You did that because you were toying with the idea of claiming treaty nonresident status or using the closer connection exception to establish nonresident alien status.
Box 9 was not checked on Form 4868 because at that point you didn’t know whether you were going to file Form 1040 or Form 1040-NR. (That’s why you filed Form 4868 on April 1, 2026).
The taxpayer is a nonresident alien who did not receive wages subject to U.S. income tax withholding. Therefore, the taxpayer’s default filing deadline is June 15, 2026.
You filed Form 4868 prior to the default deadline of June 15, 2026, so it is timely and entitles the taxpayer to an automatic six-month extension (to December 15, 2026) for filing Form 1040-NR.
You file Form 1040-NR on November 1, 2026, well within the extended deadline. You think you filed a timely income tax return.
Sometime in the future, the government’s giant computer does its matchy-matchy magic. It looks at the Form 4868 in its system and box 9 is not checked. Therefore, it assumes that the automatic extension of six months started on April 15, 2026 and extended the filing deadline to October 15, 2026.
You filed Form 1040-NR on November 1, 2026 so the big computer decides that the tax return was filed late.
Hilarity ensues.
Send a Letter
All of this can (probably) be solved with several hours of telephone calls to and/or correspondence with the IRS. You should win that fight. Reg. Section 1.6081-4(b) lists the requirements for a valid automatic extension: file Form 4868 on time, file it with the right office, and show the full amount properly estimated as tax. Box 9 is not on the list. The unchecked box is a processing problem, not a legal defect.
But here’s what I do to cut ’em off at the pass.
I send the usual letter that gets the taxpayer the usual two-month extension from October 15, 2026 to December 15, 2026. The authority for going past six months is IRC Section 6081(a), which caps extensions at six months “except in the case of taxpayers who are abroad.” The IRS describes the letter procedure in Publication 54.
- If the failure to check box 9 is a “no harm, no foul” compliance error, then Form 4868 was filed by a nonresident alien prior to the filing deadline of June 15, 2026 (April 1, 2026 is before June 15, 2026), and successfully achieved an automatic extension to December 15, 2026. The letter seeking the extension from October 15, 2026 to December 15, 2026 is a redundant safety device.
- If the failure to check box 9 is a fatal compliance error, then Form 4868 was filed prior to the April 15, 2026 filing deadline that applies generally (April 1, 2026 is before April 15, 2026), and successfully achieved an automatic extension to October 15, 2026. The letter extends the filing deadline to December 15, 2026.
Thus, no matter how the IRS sees the failure to check box 9, I’m covered.
Note: the real purpose of this is to avoid several hours of frustration in dealing with the IRS to make them see things my way.
I have a sample letter that you can plagiarize, attached below.
Who Signs the Letter?
Who is going to sign the letter?
- Best. The taxpayer must sign the letter.
- Good. What if the taxpayer can’t sign the letter? Then have the taxpayer give you a Form 2848 and you sign the letter. That’s same-same as the taxpayer signing the letter.
Logistically, both of these are a bit of a PITA. I wouldn’t blame you if you looked for a shortcut. There is one, and I suggest you only use it in an emergency.
- Adequate. A “duly authorized” person can sign the letter on behalf of the taxpayer. This is where you can get yourself in trouble.
“Duly Authorized”
A duly authorized person can sign for the taxpayer when submitting the extension request. Reg. Section 1.6081-1(b)(2) says:
“In any case in which a taxpayer is unable, by reason of illness, absence, or other good cause, to sign a request for an extension, any person standing in close personal or business relationship to the taxpayer may sign the request on his behalf, and shall be considered as a duly authorized agent for this purpose, provided the request sets forth the reasons for a signature other than the taxpayer’s and the relationship existing between the taxpayer and the signer.”
The Regulation, then, says there are two requirements you must prove:
- The reason why the taxpayer didn’t sign; and
- The relationship between you and the taxpayer.
“Reason” + “relationship” = “duly authorized agent”.
Rev. Rul. 77-463, 1977-2 C.B. 468, describes the “relationship” factor as “close personal or business relationship.” You, as the return preparer, have a close business relationship. No problem. The same ruling also holds that an extension application is not a tax return, so an attorney, certified public accountant, or enrolled agent may sign it without a power of attorney.
The “reason” part requires some proof. The taxpayer must be UNABLE to sign the extension letter “because of illness, absence, or other good cause.”
“Absence” is not defined, but I don’t think merely being outside the USA and Puerto Rico is sufficient. The reason is causal, and mere geography alone is not proof of causation, so you will need to link it explicitly to why the taxpayer is UNABLE to sign.
“Mere convenience” isn’t enough, either. This isn’t controlling for income tax returns, but in the gift tax return context, Reg. Section 25.6019-1(h) discusses gift tax returns made by agents in the event of illness, absence, or nonresidence. It says “mere convenience is not sufficient reason for authorizing an agent to make the return.” The same regulation also requires the donor to ratify an agent-made return — another sign of how strictly the IRS reads these agency rules.
So merely being out of the country is not enough. “It’s easier for my CPA to sign for me” is not enough. You need to add a clause in your letter seeking the 12/15/2026 extension deadline that explicitly asserts causation—why the taxpayer could not personally sign the extension request letter.
Here’s a sample paragraph, tailored to the scenario I describe above (box 9 not checked on Form 4868):
Taxpayer lives and is physically outside the United States and Puerto Rico. Because of that absence, and because this protective request must be placed in the U.S. mail before the disputed October 15, 2026 processing date, Taxpayer is unable as a practical matter to personally sign and timely mail this request. The undersigned CPA stands in a close business relationship with Taxpayer as Taxpayer’s tax return preparer and tax adviser for Taxpayer’s 2025 Form 1040-NR matter and signs this request on Taxpayer’s behalf under Treas. Reg. §1.6081-1(b)(2).
This will probably work. I cannot read government minds, so I don’t know how the IRS works or how it interprets the regulations or how it processes these discretionary extension request letters. One thing I do know: I do not want to live my life like Blanche Dubois and rely on the kindness of (IRS) strangers.
Summary
As a business practice:
- Get those Form 4868s mailed out well before the April 15 deadline.
- If you are filing for someone who might be filing Form 1040-NR, assume that a timely-filed Form 4868 gives you an extension of time until October 15 and send a letter requesting a further extension of time to December 15, just to be safe.
All of this is in self-defense against the whims of an arbitrary bureaucracy.
Happy Tax Season!
Sample Extension Letter
[DATE]
Department of the Treasury
Internal Revenue Service Center
Austin, TX 73301-0215
Dear Sir or Madam,
I request an extension of time to December 15, 2026 to file my 2025 individual tax return (Form 1040-NR).
Tax Status, Residence
I was a nonresident alien for the entire calendar year 2025. I live permanently in [LOCATION].
Original Filing Deadline: June 15, 2026
I was a nonresident alien individual for the entire 2025 taxable year and did not receive wages as an employee subject to withholding under chapter 24 for 2025. I use the calendar year as my taxable year.
Therefore, my prescribed filing date for the 2025 Form 1040-NR was June 15, 2026. IRC §6072(c); Treas. Reg. §1.6072-1(c).
Extended Filing Deadline: December 15, 2026
I filed Form 4868 before April 15, 2026 for my 2025 Form 1040-NR. Form 4868 was therefore timely filed. Treas. Reg. §1.6081-4(a).
A copy of my timely-filed Form 4868 is enclosed for your reference.
The timely-filed Form 4868 extended the filing deadline six months after from the original filing date (June 15, 2026) to December 15, 2026. Treas. Reg. §1.6081-4(a).
Ratification of Extended Filing Deadline
Form 4868 box 9 was inadvertently not checked.
I do not concede that the unchecked box 9 changed the prescribed filing date or invalidated the Form 4868.
However, in order to avoid any processing ambiguity, and only to the extent the IRS treats the prior Form 4868 as extending the return only to October 15, 2026, I request a discretionary additional extension of time to file the 2025 Form 1040-NR until December 15, 2026. Treas. Reg. §1.6081-1(b)(1); Pub. 519.
The additional time is requested because I live in [COUNTRY], and relevant foreign financial information is still being finalized for foreign investments and entities, which will require reconciliation and translation to complete an accurate Form 1040-NR.
Additional Information
If you need additional information, please contact [NAME], CPA, who is my return preparer:
[CPA CONTACT INFORMATION]
Thank you for your attention.
Sincerely,
[TAXPAYER]
Enclosure: Form 4868 as previously filed for 2025